Originally published January 11, 2024. Last updated September 18, 2026 with current Visa VAMP and Mastercard ECP thresholds, Mastercard’s 2025 cost-per-dispute data, a stage-by-stage lifecycle table, and cited sources throughout.
Chargeback management is the end-to-end discipline a merchant uses to handle payment disputes across their full lifecycle: preventing the disputes that can be prevented, detecting the ones that are forming, responding to and representing the ones that get filed, and feeding every outcome back into the next decision. It is broader than fighting chargebacks. Fighting is one stage of four.
The stakes have moved. Mastercard’s 2025 global chargebacks outlook projects chargeback volume climbing 24% to 324 million by 2028, and finds that merchants identify 45% of their chargebacks as fraudulent. Meanwhile the card networks tightened the ratios that decide when a dispute problem becomes a compliance problem.
This guide is for the two teams that share the problem: risk and payments leaders who own the ratio, and customer experience leaders who own the conversations that precede most disputes. It covers the chargeback lifecycle with typical timelines, what disputes really cost, where the 2026 thresholds sit, and how to build a process that treats disputes as intelligence rather than paperwork. Prevention gets its own deep treatment in our companion guide to preventing chargebacks in ecommerce in 2026.
What Is Chargeback Management?
A chargeback is a bank-initiated reversal: the cardholder disputes a charge with their issuing bank, the issuer pulls the funds back through the card network, and the merchant either accepts the loss or proves the transaction was valid. Chargeback management is everything a merchant does around that event, organized into four connected stages:
- Prevent. Screen transactions accurately, resolve complaints before they reach the bank, keep descriptors and policies clear. Our chargeback prevention guide covers this layer in depth.
- Detect. Spot disputes as they form: pre-dispute alerts, a spike in one reason code, a cluster of item-not-received claims from linked accounts, a support conversation that ends with “I’ll call my bank.”
- Respond and represent. Decide which disputes to accept and which to contest, assemble evidence that matches the reason code, and submit inside the network deadline.
- Learn. Route each outcome back to its source. A lost fraud dispute sharpens screening. A won friendly fraud case documents a repeat actor. A wave of “not as described” disputes flags a product page.
Most in-house programs are strong at stage three and weak at stages two and four, which is why they feel like an inbox rather than a system.
Chargeback vs Refund: What Is the Difference?
The chargeback vs refund distinction matters because the two events look similar to a finance team and behave completely differently for a risk team.
| Dimension | Refund | Chargeback |
|---|---|---|
| Initiated by | Customer asks the merchant | Cardholder disputes with the issuing bank |
| Controlled by | Merchant | Issuer and card network |
| Typical speed | Same day to a few business days | Weeks to months, depending on escalation |
| Cost to merchant | Refunded amount | Refunded amount, network and acquirer fees, staff time |
| Ratio impact | None | Counts toward network monitoring ratios, even if you win |
| What it signals | Routine service event | Fraud, friction, or a failed support path |
A dissatisfied customer who trusts you asks for a refund. A customer who skips you and goes to the bank is saying one of three things: the charge was not theirs, they could not resolve it with you, or the dispute button looked like an easier refund path. Our breakdown of chargeback fees and the true cost of a dispute walks through the line items.
The Chargeback Lifecycle, Stage by Stage
The chargeback lifecycle is the foundation of a workable chargeback management process, because every stage has an owner, a decision, and a clock. The timelines below are typical for Visa and Mastercard card-not-present disputes; exact windows vary by network, reason code, and acquirer, and our guide to chargeback response time limits covers deadlines network by network.
| Stage | What happens | Typical timeline | Who acts |
|---|---|---|---|
| Transaction | Order is authorized, fulfilled, and settled | Day 0 | Merchant |
| Pre-dispute inquiry or alert | Cardholder contacts the issuer; participating issuers route an alert to the merchant | Hours to a few days after the cardholder call | Issuer, merchant |
| Dispute filed | Issuer files a chargeback under a reason code; funds are debited from the merchant | Cardholder generally has up to 120 days from the transaction or expected delivery date for most reason codes, per Visa’s dispute FAQ | Issuer |
| Merchant response (representment) | Merchant accepts the dispute or submits evidence through the acquirer | Roughly 20 to 45 days from the dispute date, depending on network and acquirer | Merchant, acquirer |
| Issuer review | Issuer accepts or rejects the evidence | Typically within 30 days of the response | Issuer |
| Pre-arbitration | The losing side escalates with additional evidence or argument | Typically 30 days to file | Issuer or acquirer |
| Arbitration | The network rules on the case; the losing party pays a filing fee | Typically 10 to 45 days to file, with several weeks for a ruling | Card network |
| Resolution and learning | Funds settle to the winner; the case is closed and tagged | Total lifecycle commonly runs 30 to 120+ days | Merchant |
Two observations drive the rest of the process. The merchant controls only two windows, and both are short. And everything before the dispute is filed is the cheap part of the lifecycle; once the case exists, it counts against your ratio regardless of who wins.
How Much Do Chargebacks Cost in 2026?
The refunded amount is the visible cost. The rest is what a chargeback management program is actually paying for.
Mastercard’s 2025 analysis of the true cost of a chargeback puts merchant internal costs at an average of $82 per chargeback and external fees at an average of $46, on top of the disputed amount. The same analysis reports an average disputed amount of $110 in the US, $84 for retail, and $69 for subscription services, and forecasts the global value of chargebacks growing from $36.9 billion in 2026 to $46.1 billion in 2029. For a $70 subscription dispute, fees and labor can approach twice the value of the order.
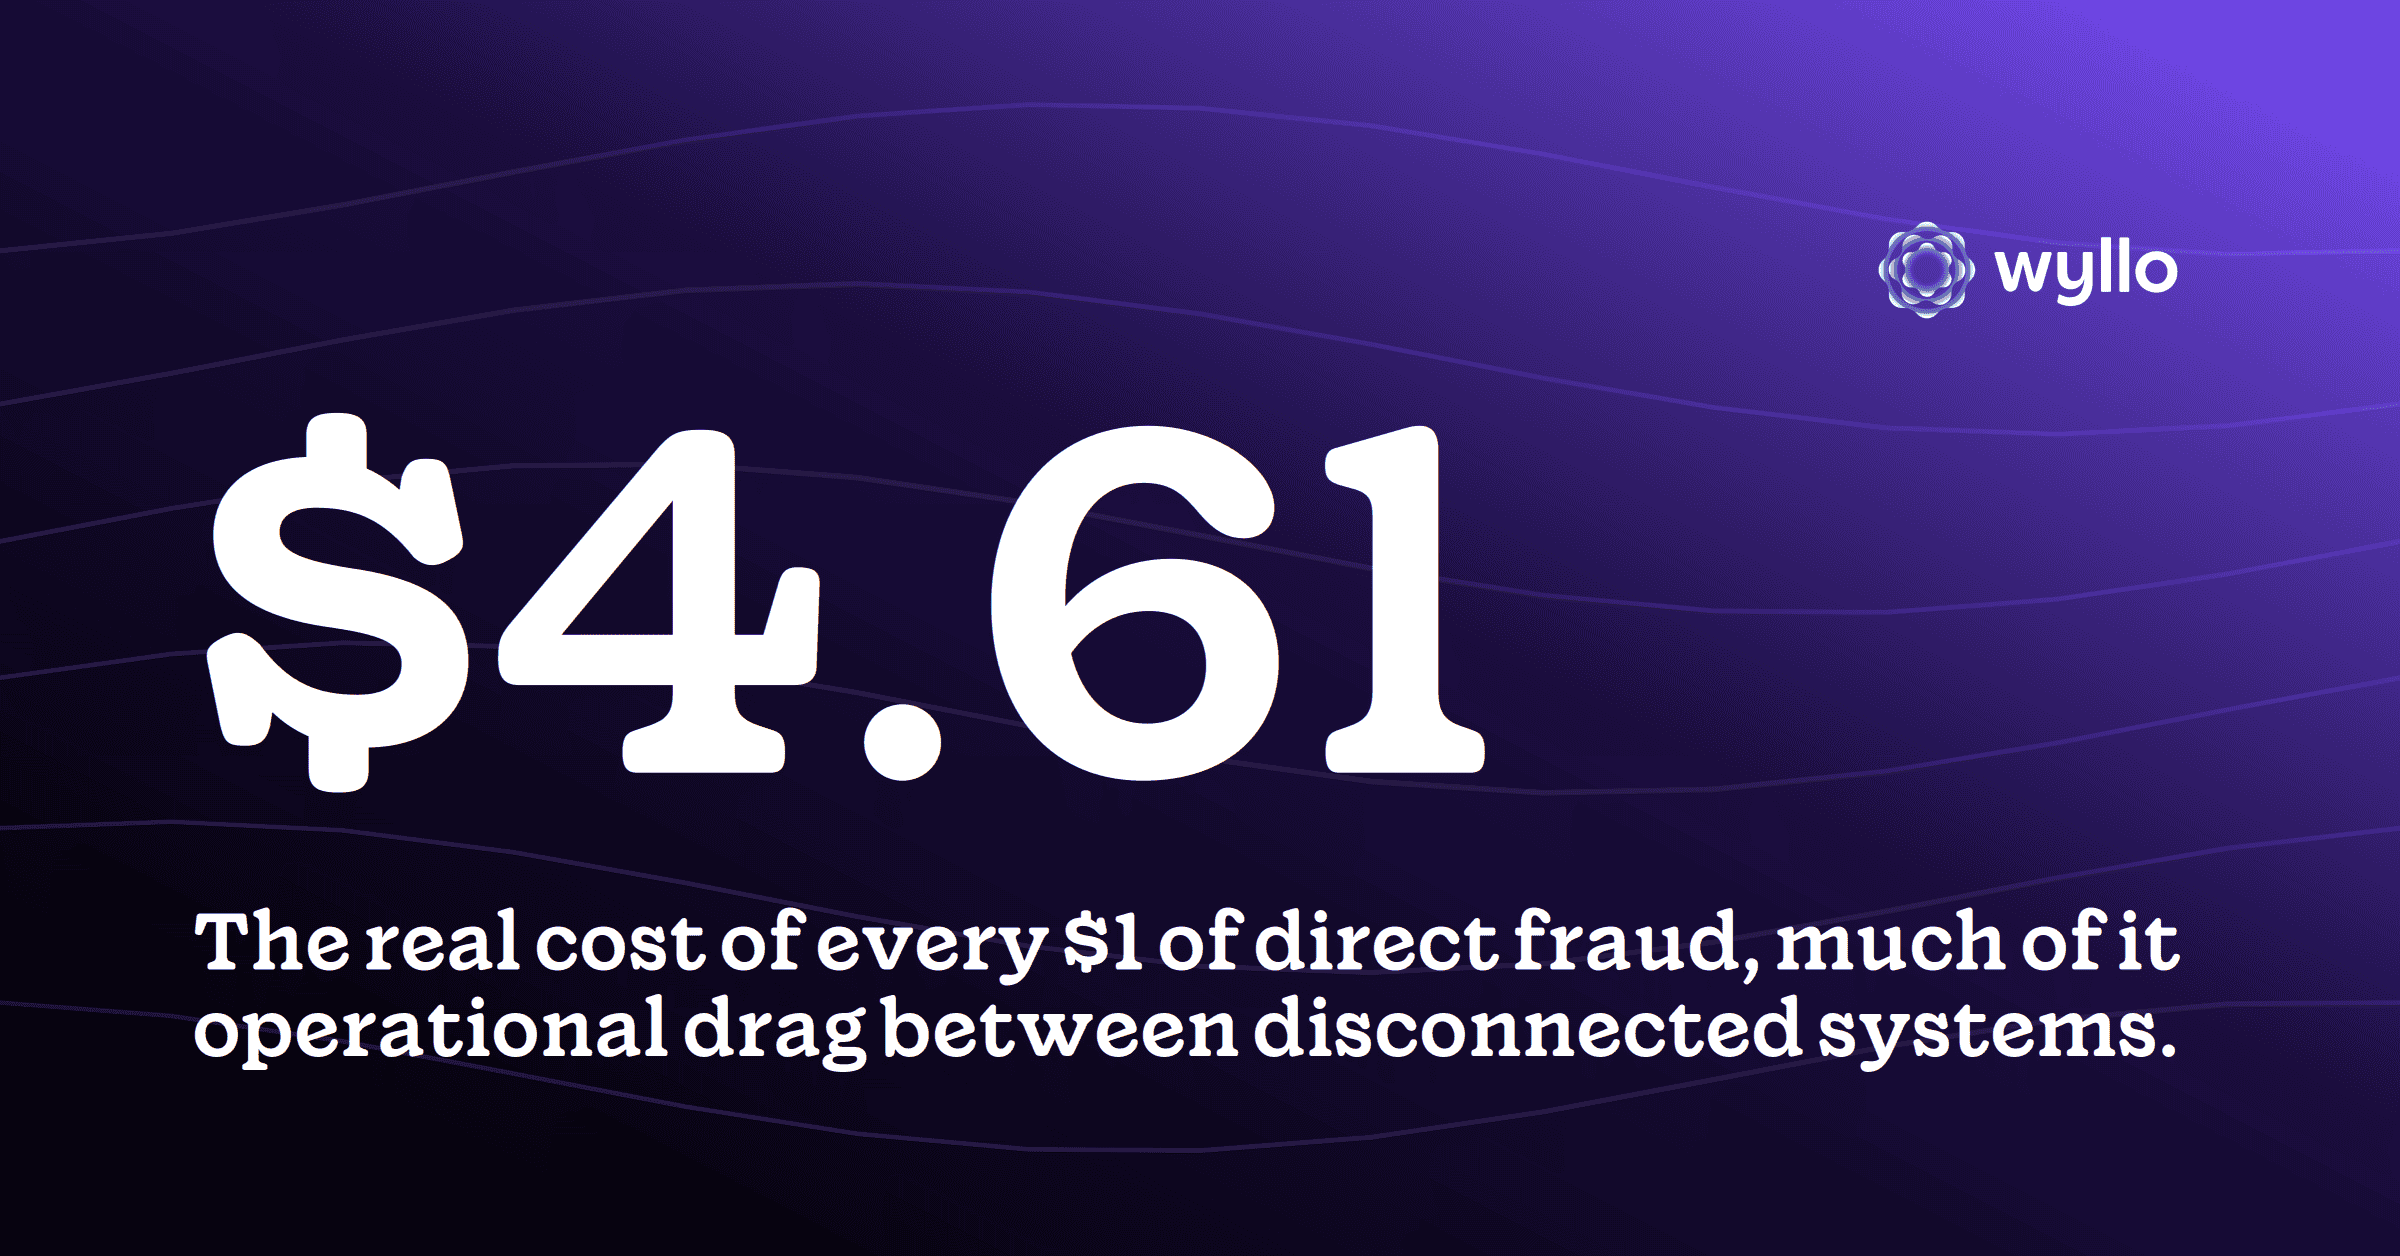
The wider fraud picture compounds this. LexisNexis Risk Solutions’ 2025 True Cost of Fraud Study finds US ecommerce and retail merchants absorb $4.61 in total costs for every $1 of fraud lost, and the Merchant Risk Council’s 2026 Global Payments and Fraud Report, based on 1,278 merchant professionals across 37 countries, puts revenue lost to payment fraud at 3.2% of annual ecommerce revenue globally.
Add the costs no fee schedule shows: inventory that will not return, a processor relationship under review, a customer who now associates your brand with a payment problem. If moving the headline number is the goal, start with our guide on how to reduce your chargeback rate.
What Are the Network Monitoring Thresholds in 2026?
Ratios are where chargeback management stops being a cost question and becomes a continuity question. Both major networks run monitoring programs, and both changed them recently.
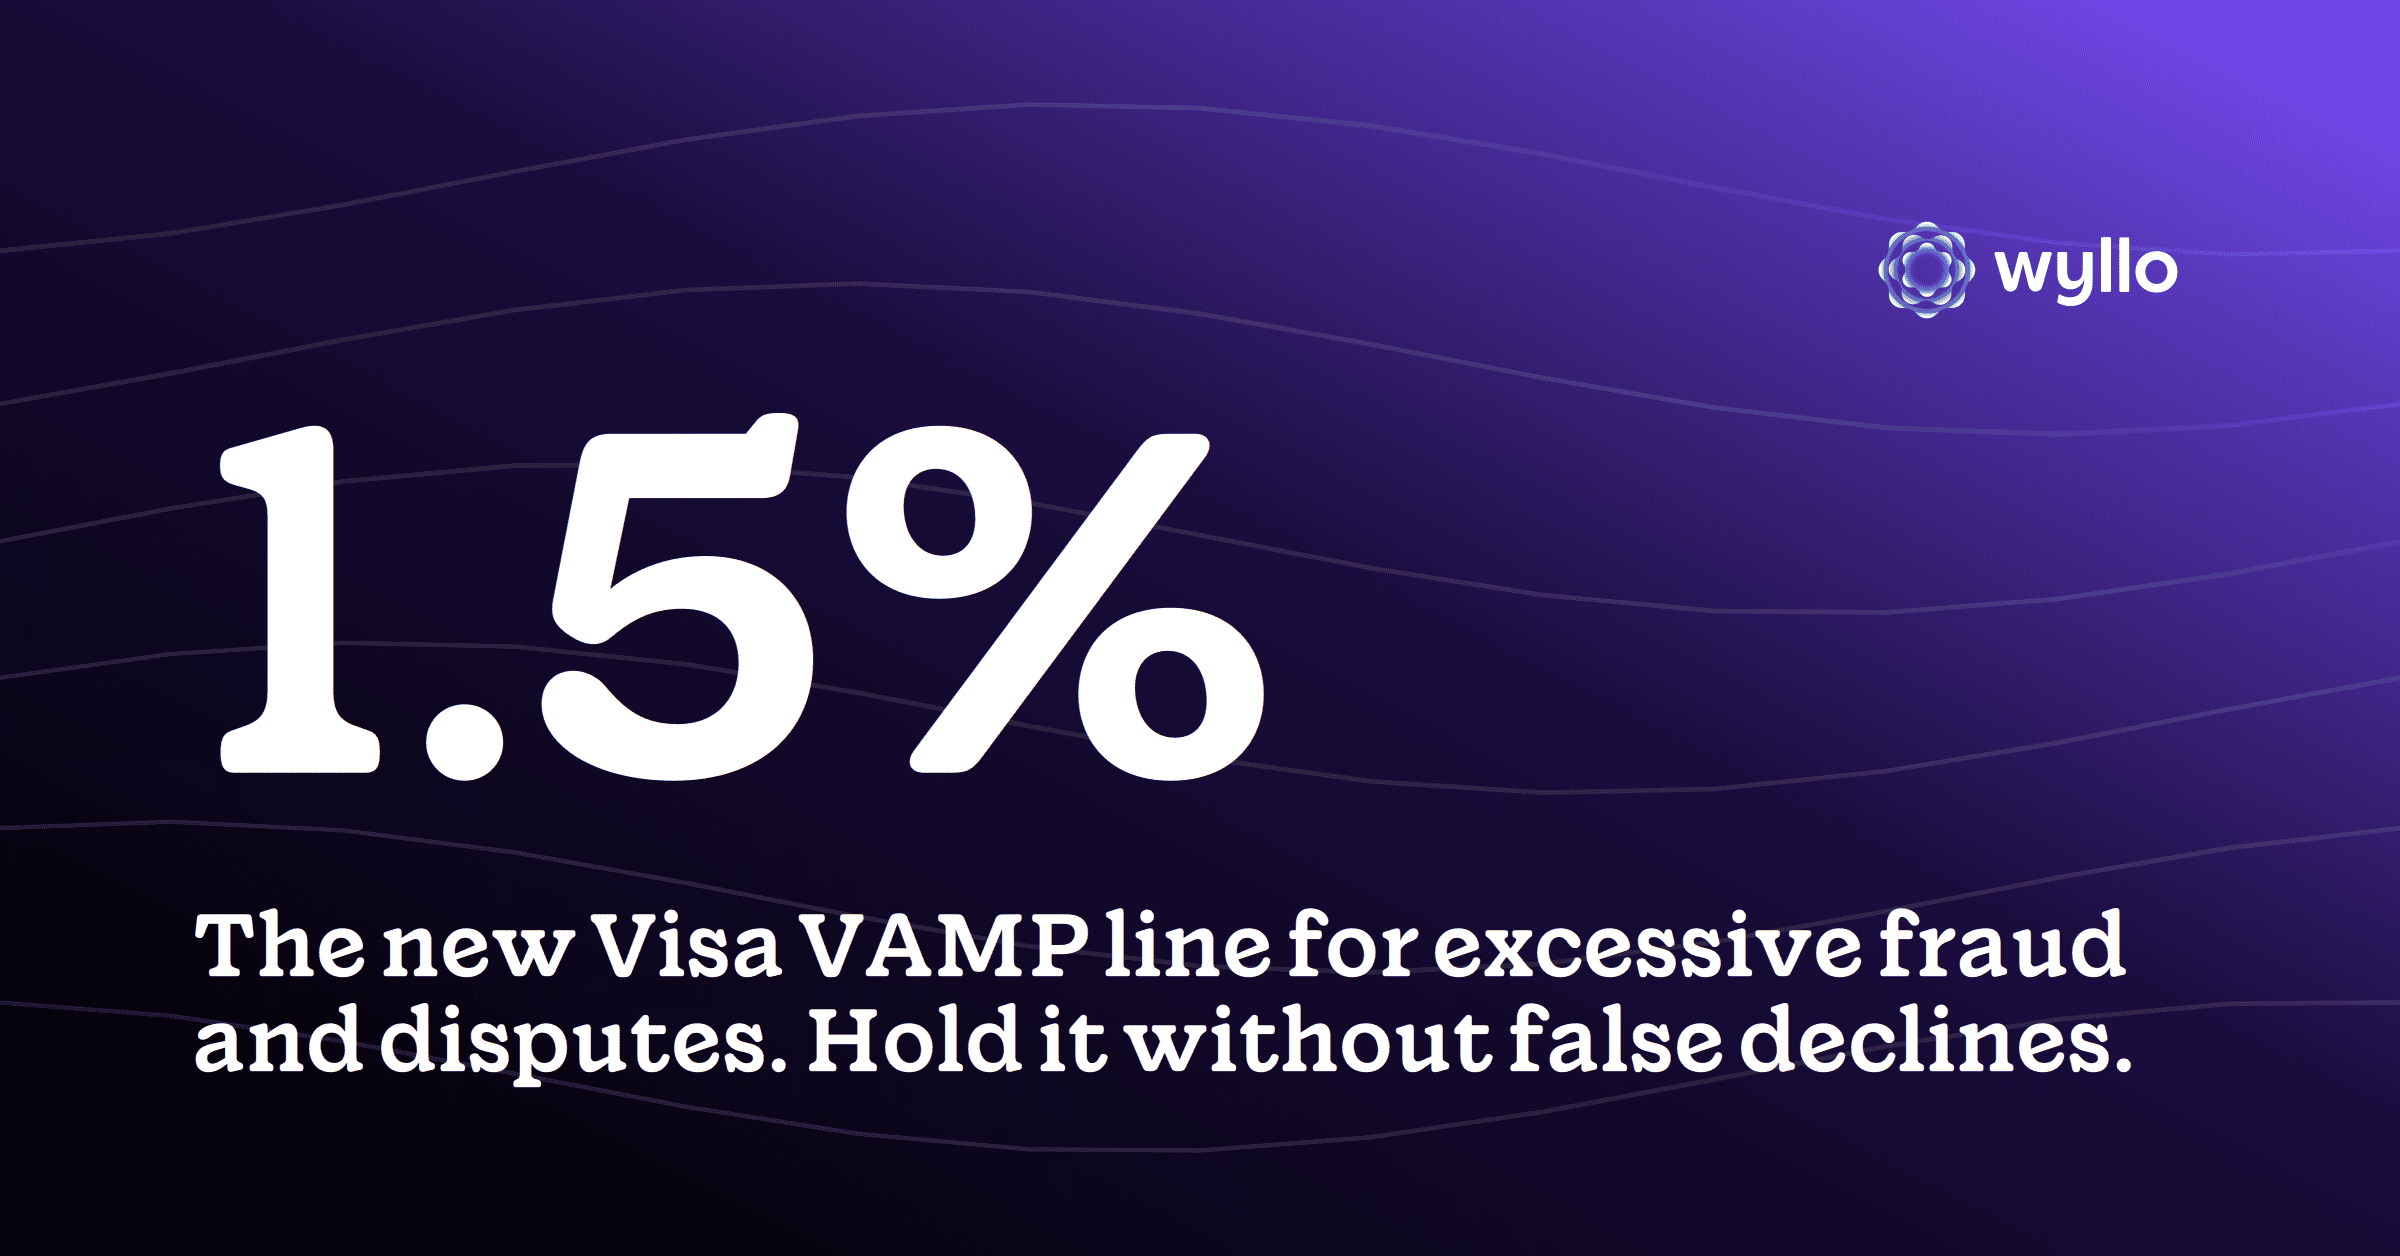
Visa Acquirer Monitoring Program (VAMP). Visa consolidated fraud and dispute monitoring into one program with one ratio. According to the Merchant Risk Council’s summary of the current VAMP thresholds, the merchant-level “excessive” threshold dropped from 2.2% to 1.5% on April 1, 2026. The ratio is reported fraudulent transactions (TC40) plus total disputes (TC15) divided by settled card-not-present transactions; merchants enrolled in the program are assessed $8 per fraudulent or disputed transaction, and a first violation within a rolling twelve months receives a three-month grace period before enrollment.
Mastercard Excessive Chargeback Program (ECP). Per J.P. Morgan’s merchant guide to the Mastercard Excessive Chargeback Program, an Excessive Chargeback Merchant (ECM) has at least 100 chargebacks in a calendar month and a chargeback-to-transaction ratio of 1.50% or higher, and a High Excessive Chargeback Merchant (HECM) has at least 300 chargebacks and a ratio of 3.00% or higher. The ratio divides the month’s chargebacks by the previous month’s sales count, and assessments escalate monthly, reaching 5,000 (USD or EUR) for ECM and 10,000 for HECM by months four through six.
Two notes. Rules keep changing, so confirm current numbers and counting treatment with your acquirer in writing. And a won representment recovers revenue but does not remove the dispute from either ratio, which is the strongest argument for investing upstream.
Why Do Customers File Chargebacks?
Every dispute lands in one of three buckets, and dispute management in ecommerce gets easier once your reporting separates them.
Third-party fraud. A stolen card or a taken-over account produced a transaction the cardholder did not make. The dispute is legitimate, and the only durable fix is stopping the order at checkout.
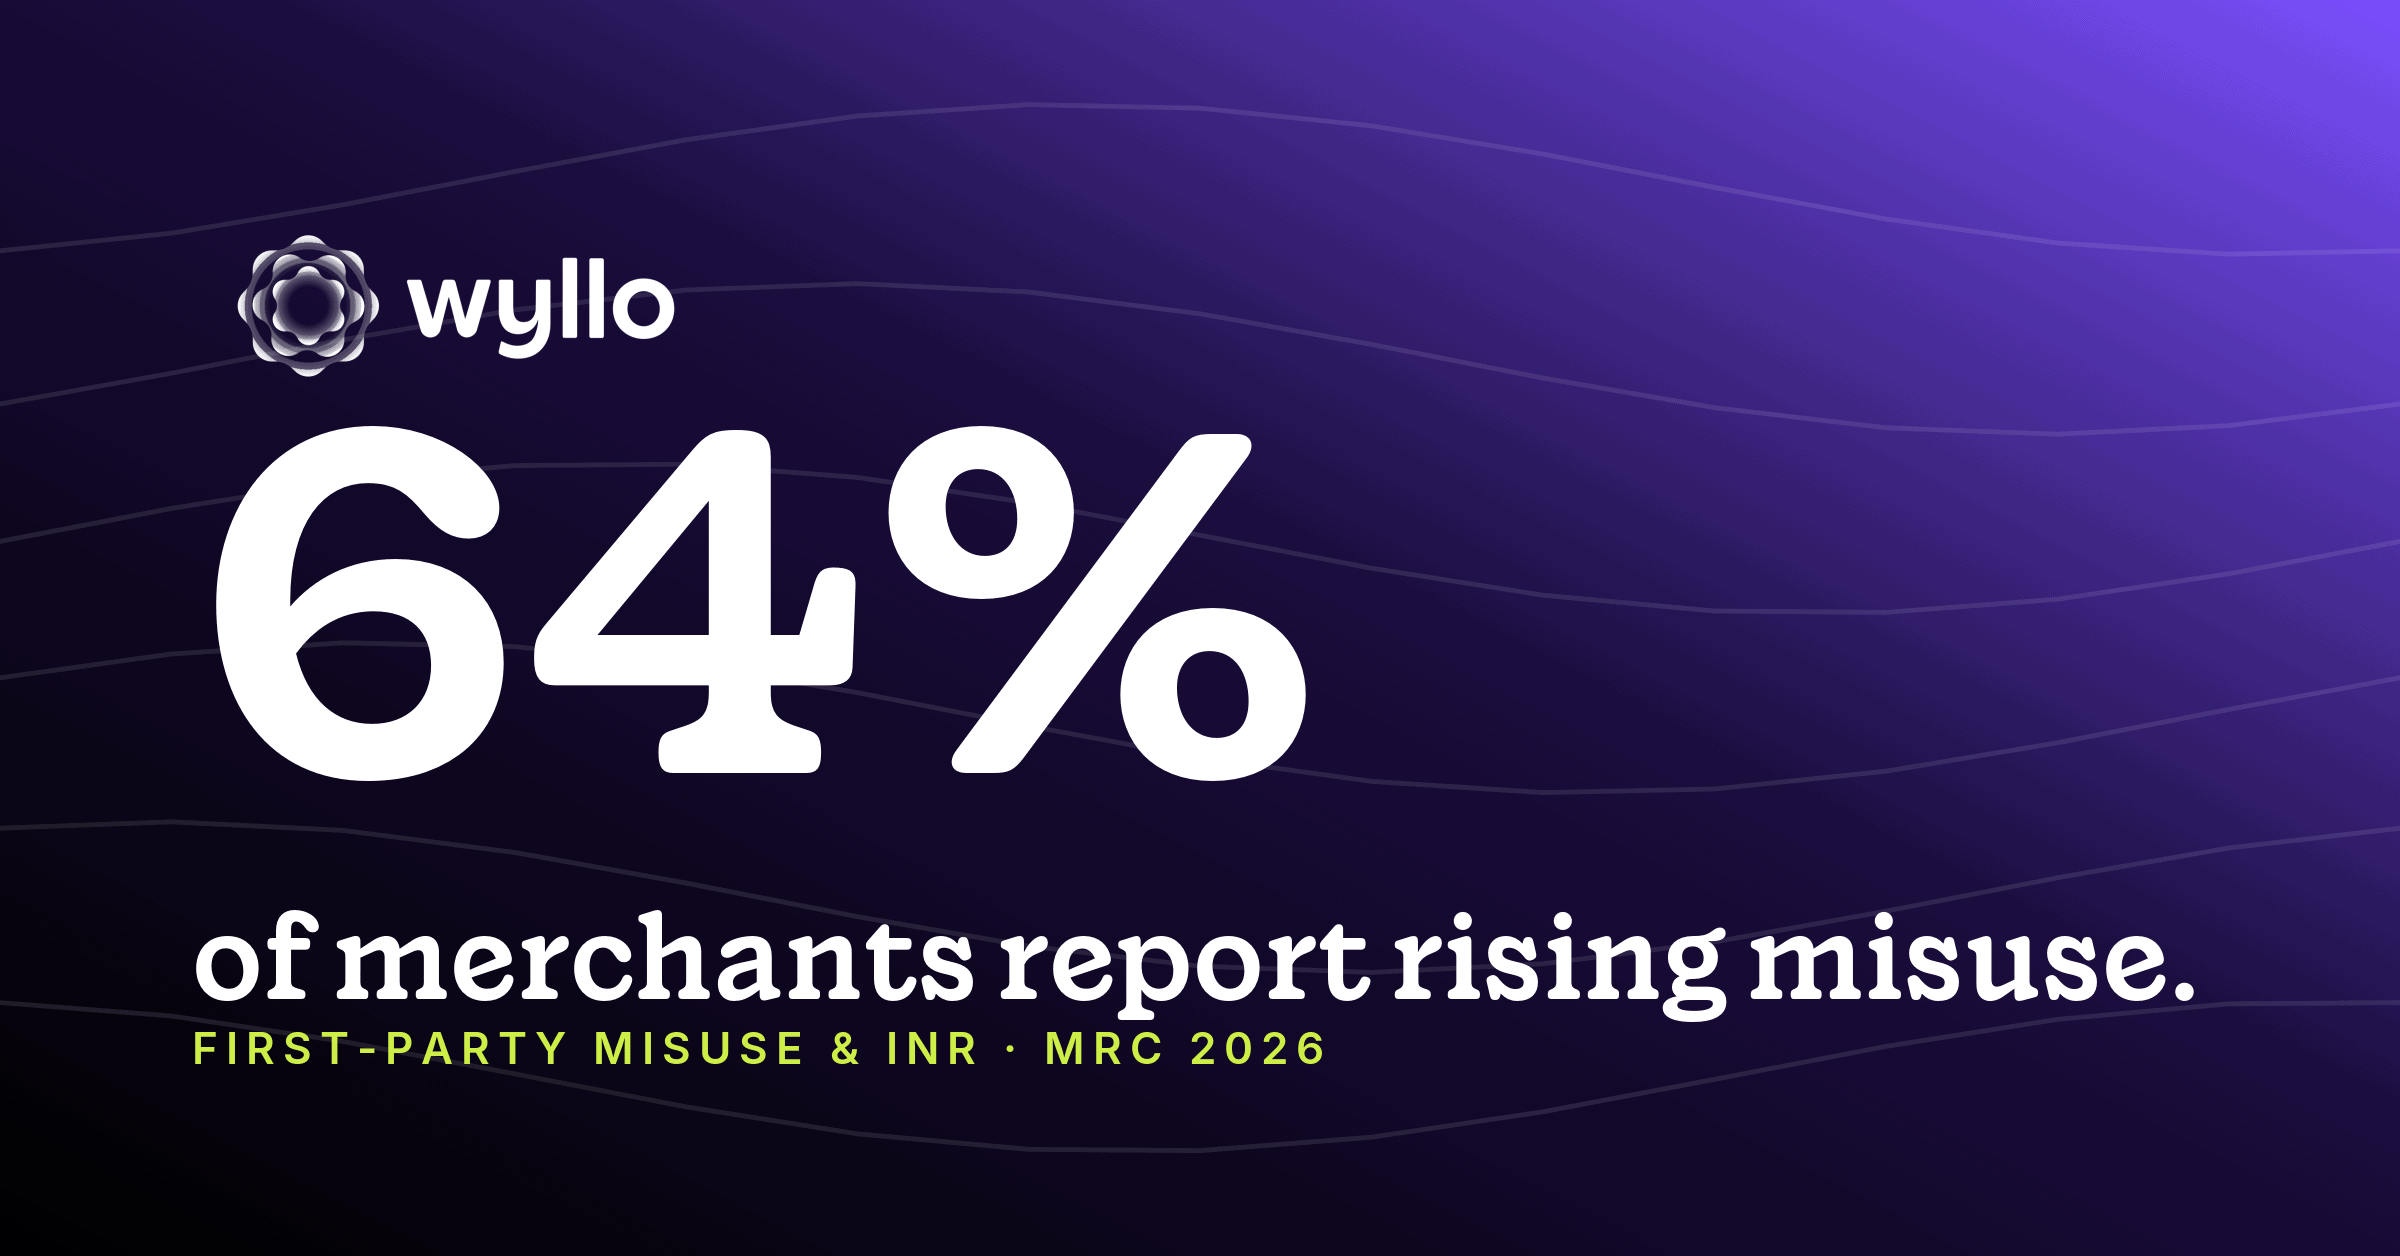
First-party misuse (friendly fraud). The cardholder made the purchase and disputed it anyway, sometimes by honest mistake (Mastercard’s true cost research reports that 48% of consumers have mistakenly disputed a legitimate charge), sometimes opportunistically or serially. Visa’s friendly fraud insights estimate first-party misuse at around 20% of fraudulent disputes globally and up to 30% for high volume online merchants, and the MRC’s 2026 report found 62% of merchants reporting increased first-party misuse disputes over the past year.
Merchant error and confusion. An unclear billing descriptor, a slow refund, an unexpected subscription renewal, a missing delivery update, a support queue slower than the bank’s phone line. These are self-inflicted and the cheapest to eliminate.
The buckets route to different owners: third-party fraud to the fraud team, merchant error to CX and operations, and first-party misuse in between, which is why it grows fastest where risk and CX do not share data. Our field guide to the five signs a chargeback is actually fraud helps teams sort the middle bucket case by case.
How to Build a Chargeback Management Process
A workable process gives each lifecycle stage a decision rule, an owner, and a measurement.
Stage 1: Prevent, and Measure Prevention Honestly
Prevention is the largest lever, covered in full in the 2026 chargeback prevention guide. For the wider process, two disciplines matter most: grade screening on approval rate and fraud rate together, because a program that “wins” by declining good customers trades disputes for lost revenue; and keep merchant-error disputes on their own reporting line, because they are the easiest number to drive toward zero.
Stage 2: Detect Disputes While They Are Still Cheap
The window between a cardholder’s complaint and a filed chargeback is where strong programs earn their margin. Network alert rails on both Visa and Mastercard notify participating merchants when a cardholder contacts their issuer, and speed matters: Mastercard’s 2026 case study with Fiserv reports that of the alerts merchants resolved stemming from a Fiserv issuer dispute, 80% were resolved in less than 24 hours, preventing the chargeback entirely.
Detection also lives in your own data. A support ticket that mentions the bank, a refund request from an account linked by device to three prior item-not-received claims, a failed cancellation attempt: these are disputes in formation, and the merchants who catch them are the ones whose agents can see risk context inside the conversation.
Stage 3: Respond and Represent With Intent
Not every dispute should be fought. A sound response rule sorts cases by reason code, order value, evidence strength, and customer history, then accepts the ones you will lose and represents the ones you can win. Our guide to chargeback representment covers evidence assembly in detail; the process points are these.
Capture evidence at order time, not dispute time. Under Visa’s Compelling Evidence 3.0 rules, a merchant contesting a card-absent fraud dispute (condition 10.4) can prevail by showing two prior undisputed transactions from the same cardholder, between 120 and 365 days old, where at least two core data elements match and one is the IP address or device ID. That only works if you stored those elements for every order, and Visa reports that nearly 90% of enterprise merchants now use compelling evidence, so the bar for “prepared” has risen.
Match the package to the reason code: product pages and correspondence for “not as described,” delivery proof for item not received, identity and history for fraud. Our reference on chargeback reason codes maps each family to the evidence that moves issuers. And submit early; the merchant’s window is the shortest in the lifecycle.
Stage 4: Learn, and Close the Loop
This stage turns chargeback management from an inbox into intelligence. Each closed case carries a tag: source bucket, reason code, outcome, and what would have changed it. Lost fraud disputes go to the screening model. Won friendly fraud cases go to the customer record, so the same actor is recognized at their next order or refund request. Merchant-error disputes go to whoever owns the descriptor, the product page, or the cancellation flow. The test: what share of last quarter’s disputes came from a pattern you had already identified?
What to Look for in Chargeback Management Software
When evaluating chargeback management software in 2026, look for full lifecycle scope (prevention signals, alerts, representment, and outcome analytics, not representment alone) and four capabilities that separate a tool that handles disputes from a platform that reduces them:
- Order-time evidence capture and reason-code-aware automation. Per-order IP, device, account, and delivery data, assembled into packages built for the specific network condition, with human review where judgment moves the outcome.
- Ratio tracking the network’s way. VAMP-style and ECP-style ratios computed as the networks compute them, with alerting well below the enforcement lines.
- Repeat-actor linking. Seeing that three “different” customers share a device or address, because serial first-party misuse hides in the gaps between identities.
- Context inside the workflow. Risk signals delivered where support, ops, and finance already work, rather than in another dashboard.
Where Risk and CX Meet
A chargeback is a customer experience event recorded as a payment event. Most first-party misuse passes through a human conversation first: a refund request, a “where is my order,” a cancellation attempt. Whoever handles that conversation decides, usually without knowing it, whether a dispute gets filed.
The same signals that flag risk at checkout (device history, account age, prior claims, linked identities) also predict who is about to dispute and who genuinely needs help. With those signals in view, an agent can refund a trusted customer instantly, verify a suspicious claim, and log the interaction that becomes representment evidence later. Without them, the agent either gives away margin or manufactures the next chargeback. For CX leaders, the ask is to insist that risk context reach the conversation; for risk leaders, to treat support and post-purchase data as first-class inputs.
How Wyllo Helps
Every stage works better when the stages share one view of the customer, because the signal that would have prevented a dispute rarely lives in the system where the dispute lands. That is the design premise of Wyllo, the risk intelligence platform for commerce: intent-aware decisioning that connects checkout, claims, support, and chargeback data so the pattern seen in one place informs the decision in the next.
- Wyllo Chargeback Management runs the response and representment stages end to end: dispute workflows, reason-code-matched evidence, expert analyst review, and outcome reporting, with chargeback protection for eligible orders.
- Wyllo Payment Fraud Protection screens every transaction with AI plus human fraud analysts, stopping the third-party fraud that becomes tomorrow’s disputes while protecting approval rates.
- Wyllo Claim and Policy Abuse Prevention risk-scores refund requests, item-not-received claims, and policy exceptions, and links repeat actors across identities, so first-party misuse is caught before it becomes a chargeback.
- Wyllo CX Support puts risk scores and next-best actions inside the support tools your team already uses, so the conversation that precedes most disputes gets resolved with context.
Less reaction. More reason.
Frequently Asked Questions
What is chargeback management?
Chargeback management is the end-to-end discipline a merchant uses to handle payment disputes across their lifecycle: preventing avoidable disputes, detecting disputes as they form through alerts and internal signals, responding to filed chargebacks with reason-code-matched evidence inside network deadlines, and feeding outcomes back into screening, policy, and customer records. It is measured on dispute ratio, win rate, and the share of disputes prevented, not on win rate alone.
What is the difference between a chargeback and a refund?
A refund is initiated and controlled by the merchant: the customer asks, the merchant approves, funds return within days. A chargeback is initiated by the cardholder through their issuing bank: the issuer reverses the funds, the merchant pays network and acquirer fees on top of the amount, and the dispute counts toward Visa and Mastercard monitoring ratios even if the merchant later wins. A refund is a service event; a chargeback is a risk signal.
How long does the chargeback lifecycle take?
Cardholders generally have up to 120 days from the transaction or expected delivery date to file for most reason codes, according to Visa’s dispute FAQ. Merchants then typically have 20 to 45 days to respond depending on network and acquirer, issuers review within about 30 days, and pre-arbitration and arbitration can add weeks more. A straightforward case resolves in roughly a month; an escalated one can run 120 days or longer.
What chargeback ratio triggers a network monitoring program in 2026?
Under Visa’s VAMP, the merchant “excessive” threshold is a 1.5% ratio of reported fraud plus disputes against settled card-not-present transactions as of April 1, 2026, per the Merchant Risk Council’s threshold summary. Under Mastercard’s ECP, an Excessive Chargeback Merchant has at least 100 chargebacks in a month and a ratio of 1.50% or higher, and a High Excessive Chargeback Merchant at least 300 and 3.00% or higher, per J.P. Morgan’s program guide. Confirm current figures with your acquirer.
What is friendly fraud and how big a problem is it?
Friendly fraud, also called first-party misuse, is when a cardholder disputes a purchase they actually made, whether by mistake, to avoid a return, or deliberately to keep goods and money. Visa estimates it accounts for around 20% of fraudulent disputes globally and up to 30% for high volume online merchants, and the MRC’s 2026 Global Payments and Fraud Report found 62% of merchants reporting an increase in first-party misuse disputes over the past year.
Should I fight every chargeback?
No. A sound response rule sorts disputes by reason code, order value, evidence strength, and customer history, then accepts the cases you are likely to lose and represents the ones your evidence supports. Fighting everything lowers win rates and consumes analyst time; fighting selectively, and tagging every outcome so the pattern feeds prevention, produces better economics.
Bringing It Together
Chargeback management in 2026 is a lifecycle, not a mailbox. The merchants with the healthiest ratios prevent what can be prevented, detect disputes while they are still a phone call, represent the cases their evidence supports, and treat every outcome as information about the next order, claim, and support conversation.
The direction of travel is clear. Dispute volume is rising, first-party misuse is rising faster, and network thresholds are tighter than two years ago. Those forces reward merchants who connect the stages and bring risk and CX into the same view of the customer.
Curious how an intent-aware risk intelligence approach would change your dispute ratio, your win rate, and the conversations that precede both? Start with Wyllo Chargeback Management for the response and representment layer, or explore the broader Wyllo platform for connected intelligence across the full customer journey.